“Miami’s luxury condo market has become a billion-dollar-per-quarter industry in 2026, reflecting a city that continues to attract high-net-worth buyers and generate substantial capital. While cyclical patterns and broader market headwinds are inevitable, Miami’s long-term future is underpinned by a strong foundation.”
— Sep Niakan, Founder & CEO of Blackbook Properties
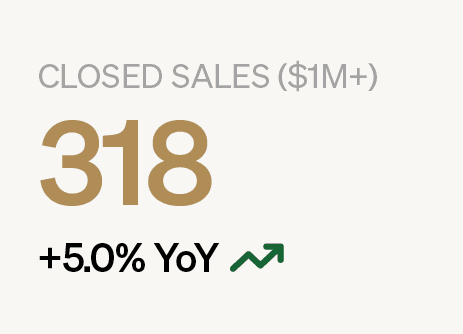
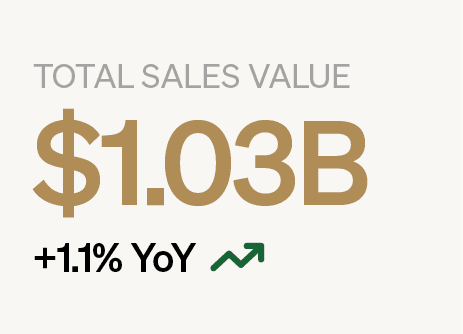
Q3 2026 saw several of the trends that shaped Miami’s luxury condo market earlier this year continue to play out. Sales increased 5% year-over-year, while total dollar volume edged up 1.1% to $1.029 billion, extending the market’s positive sales momentum into the traditionally slower half of the year.
As we've seen in previous quarters, price performance varied by tier and location. The $2–5M segment led the quarter in sales and dollar-volume growth, while waterfront properties dominated its most expensive sales.
Our Q3 2026 Miami luxury condo market analysis breaks down what these shifts signal for buyers, investors, and sellers, identifying where pricing momentum is building, which segments may face greater constraints on future appreciation, and delivering the market intelligence needed to make informed decisions. Read on for the full story.
 |
 |
 |
 |
 |
 |
This luxury condo market report only includes data for properties in Coastal Mainland Miami and Miami Beach priced $1 million and above. The Coastal Mainland Miami grouping covers Brickell, Downtown Miami, Edgewater (including Arts & Entertainment District), Coconut Grove, and Coral Gables. The Miami Beach grouping covers South Beach, Mid- & North Beach, Surfside & Bal Harbour, Sunny Isles Beach, and Fisher Island.
Contrasting Q2 2026, we have returned to the $1M+ price threshold for Q3 2026 to provide a more comprehensive overview of Miami’s luxury condo market. We’ve also expanded our market coverage to include a deeper analysis of four price tiers: Premium ($1–2M), Luxury ($2–5M), High Luxury ($5–10M), and Ultra Luxury ($10M+).
— Key Players in Miami’s Luxury Condo Market
Brickell Gains Traction Despite Inventory Surplus
Miami’s financial hub gained momentum in Q3 2026 with a 36% year-over-year sales growth, a 73% surge in transacted dollar volume (to $75 million), and a 9% increase in median prices. Despite Brickell possessing one of Miami’s highest inventory levels, its positive performance regarding sales and prices makes it a key market to watch.
Coconut Grove Experiences Price Gains Amid Lean Supply
Coconut Grove stood out as Miami’s only seller’s market in Q3 2026. While sales were mostly flat year-over-year (45 vs. 46), the median price rose 27.4% as closings concentrated in the $2–5M and $5–10M tiers. Of interest was a record-setting, $16.15-million penthouse sale at Mr. C Residences Bayshore Tower. Total dollar volume also climbed 46% year-over-year to $142.2 million.
Tight supply and notable price appreciation keep Coconut Grove firmly on our radar of key markets in Miami.
Surfside & Bal Harbour See Trophy Sales Leading the Way
With some of Miami’s most expensive Q3 2026 closings taking place here, ultra-luxury sales continued driving the area’s performance for a second consecutive quarter. The pairing recorded $208 million in total dollar volume, the highest among the ten neighborhoods we analyzed.
Despite a 24% year-over-year decline in median price to $3.1 million, Surfside & Bal Harbour posted Miami’s second-highest median price, underscoring continued strength at the upper end of their combined market.
— Q3 2026 Miami Luxury Condo Market Highlights
For Pricing, Still Waters Run Deep
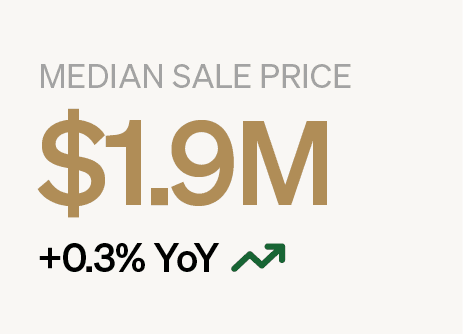
On the surface, Miami’s $1M+ condo market appears steady, with the median sale price essentially flat at $1.9 million in Q3 2026. However, this broader number tells only part of the story.
Recently delivered new-construction condos have helped keep the overall median price elevated, supporting the headline figures that suggest stability even as prices have followed a slight downward trajectory in parts of the market.
A deeper analysis by price tier reveals that the upper end of the market recorded higher median sale prices despite fewer transactions. The $5–10M tier saw its median increase 8.7% year-over-year, while the $10M+ tier posted a 15.1% increase.
Coastal Mainland Miami vs. Miami Beach ($1M+)
Coastal Mainland Miami recorded stronger year-over-year performance, with median sale prices rising 3.2% alongside higher sales activity. By comparison, Miami Beach remained largely flat, with median sale prices up just 0.5% as both prices and sales held relatively steady.
Top 3 Most Expensive Sales in Q3 2026
-
4-bedroom, 5.5-bathroom upper-floor unit at The Surf Club Four Seasons Hotel and Residences for $30,250,000
-
4-bedroom, 5.5-bathroom corner unit at The Surf Club Four Seasons Hotel and Residences for $25,600,000
-
Two-story upper penthouse at Oceana Bal Harbour for $22,000,000
Luxury buyers are becoming increasingly more selective, but one priority remains unchanged: direct water views. All three of Q3’s top sales took place in Surfside & Bal Harbour, reinforcing the continued appeal of waterfront properties in established coastal enclaves.
Are Miami Condo Prices Dropping in 2026 or 2027?
Several pockets of Miami’s $1M+ condo market are likely to see price declines, even if broader market statistics do not fully reflect this.
Based on our observations as luxury condo experts, Airbnb-oriented properties, in particular, could face significant price pressure over the next one to two years. We may also see modest declines in segments more dependent on financing, especially the $1–2M band, where higher mortgage rates can weigh more heavily on buyers.
Another area to watch is newly delivered preconstruction inventory. Owners looking to sell immediately after completion may face stiff competition from other units entering the market simultaneously. This pressure is often most pronounced during the first six months after delivery, with pricing typically taking around 18 months to stabilize.
But not all condos face the same outlook. Waterfront and water-view homes continue to attract stronger buyer interest and generally outperform comparable units without these features. Demand also remains stronger for end-user residences as opposed to investor-oriented product.
— Price-Tier Analysis
Sales Momentum Led by the $1–5M Segment
Miami’s luxury condo market recorded 318 closed sales in Q3 2026, up 5% from 303 in Q3 last year. This marks the third consecutive quarter of higher sales compared to 2025, following gains of 16.5% in Q1 and 4.4% in Q2.
The $1–2M segment accounted for the largest share of sales at 51.6%, while the $2-5M segment ranked second at 34.6% and posted the strongest year-over-year sales growth at 18.3%.
Coastal Mainland Miami vs. Miami Beach ($1M+)
Continuing the trend established in Q1 and Q2, Coastal Mainland Miami once again outperformed Miami Beach in year-over-year sales growth this third quarter. Sales rose 9.8%, from 132 to 145, while Miami Beach trailed with a more modest 1.2% year-over-year increase, from 171 to 173.
Q4 2026 Sales Outlook
As predicted in our Q2 report, Miami’s luxury condo market recorded higher sales year-over-year despite the seasonal slowdown typical of the second half of the year. Looking ahead, we expect sales to remain stable. Lower prices in most segments have improved buyer appeal, although headwinds such as rising mortgage rates could continue to weigh on demand in the sub-$2M segment.
Inventory Shrinks but Buyers Retain Leverage
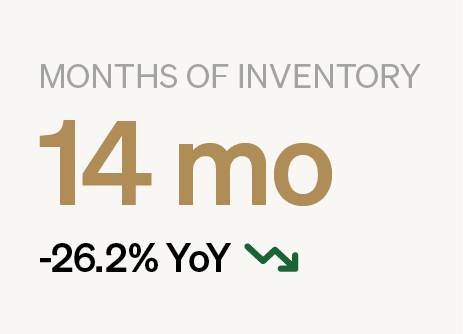
Months of inventory declined 26.2% year-over-year, from 19 to 14 months in Q3 2026. Of all the price tiers in our analysis, the $5–10M High Luxury segment faces the greatest supply pressure, with 20 months of inventory offering buyers the strongest negotiating leverage.
In line with our previous forecast, the market moved closer to balance, although inventory above the 9–12-month range continues to favor buyers. Looking ahead, we expect buyer-friendly conditions to persist through Q2 2027, with inventory potentially stabilizing or rising in Q4 2026.
Coastal Mainland Miami vs. Miami Beach ($1M+)
Tighter inventory across Miami Beach submarkets continued to afford sellers with greater negotiating leverage compared to their Coastal Mainland counterparts.
| Download the full analysis of Miami’s $1–10M+ luxury condo market. |
— Preconstruction Spotlight
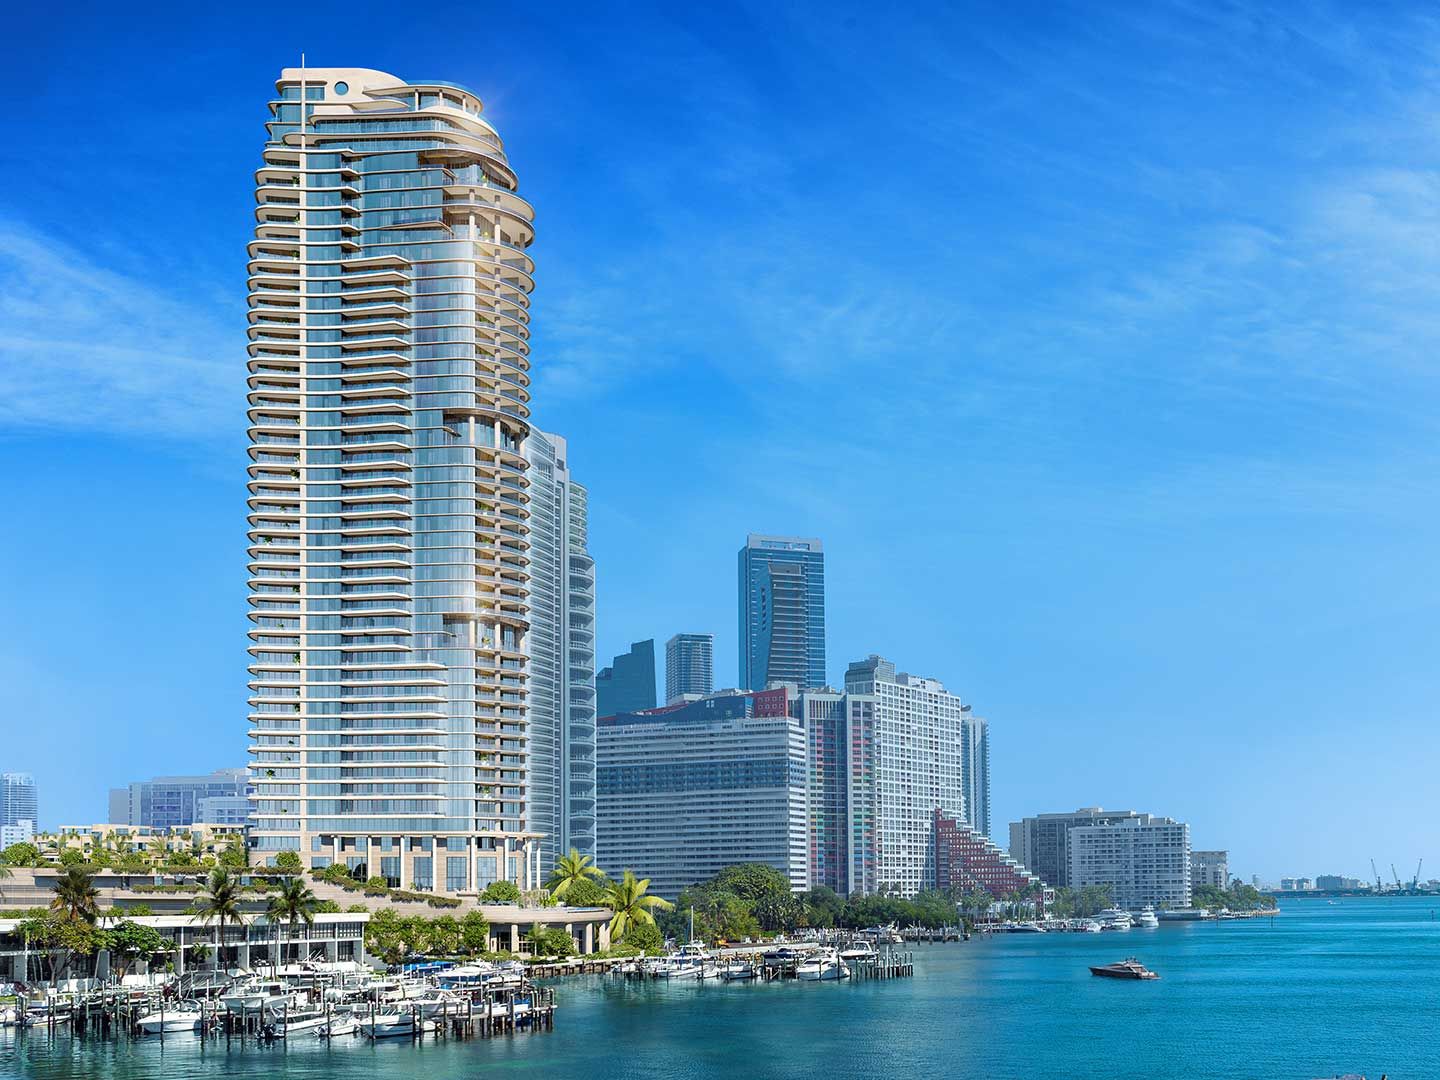
Branded residences, landmark hotel redevelopments, and record-setting penthouse deals defined Miami’s luxury condo preconstruction landscape in Q3 2026.
Casa Bella Residences by B&B Italia was completed in Arts & Entertainment District, adding another standout residence to Miami’s growing collection of design-led luxury properties. The quarter also brought major announcements, with Bugatti-branded residences set to make their US debut in Brickell and the historic Savoy Hotel & Beach Club slated for redevelopment and expansion in Miami Beach.
The Charles Penthouse at the St. Regis Residences Miami in Brickell ranked among the quarter’s biggest headlines. Going under contract for $47 million, it marked one of the largest and highest-priced condo transactions in Brickell’s history. Spanning 10,012 square feet across two levels, the five-bedroom, seven-bath residence features a private rooftop pool, a spa, a summer kitchen, and two expansive terraces overlooking Biscayne Bay.
Disclaimer: Preconstruction condo sales have been excluded from this report. Such transactions are not tracked consistently through the MLS, limiting reliable comparisons with the resale market.
— 2026 Predictions
Continued Business and Wealth Migration
One of the most significant shifts we’re seeing is that Miami is no longer just a destination for luxury second homes. More buyers are relocating to the Magic City on a permanent basis and establishing businesses, raising families, and investing in the community.
With major recent developments such as Carnegie Mellon’s planned Wynwood campus, backed by Ken Griffin’s historic $3-billion funding commitment, South Florida is further cementing its position as a growing center of wealth and influence.
Headwinds vs. Tailwinds
HOA fees in Miami are now the third-highest in the country, with rising mortgage rates also weighing on the more financing-sensitive segments.
Conversely, Miami’s world-class lifestyle, business-friendly environment, favorable personal-income-tax structure, and the recent approval of additional tax relief for primary homeowners through Florida’s Amendment 3 remain major points of strength.
Speaking from over 20 years of luxury real-estate experience, we expect the tailwinds to prevail in the long term, continuing to attract affluent individuals and families to South Florida’s sunny shores.
End-User vs. Investor Product
Miami’s luxury condo market currently favors end users over investors as rents have remained relatively steady while ownership costs and mortgage rates have risen in recent years, compressing returns.
In today’s market, the case for homebuyers in Miami is considerably stronger than for those purchasing solely to generate rental income.
— Learn More
With sales holding up in Q3 despite the seasonal slowdown, we anticipate a steady pace of activity through the end of 2026. Performance still varies considerably across neighborhoods and price tiers, making a more granular analysis essential to understanding local market conditions and identifying opportunities.
For a complete picture of the Q3 2026 overall Miami luxury condo market—including neighborhood-specific insights, emerging opportunities for buyers and sellers, and more data-based predictions—download our full report below.